|

Industry specialists anticipate that tariff pressure will primarily affect lower-margin product lines first
US 19% Tariff Threatens Competitiveness of Thai Tuna and Shrimp
 THAILAND
Friday, August 07, 2026, 00:10 (GMT + 9)
The measure imposed by Washington puts pressure on export margins, reduces seafood sector sales projections, and reshapes competition against countries such as Ecuador, India, and Vietnam.
The confirmation of a 19% reciprocal tariff rate by the Office of the United States Trade Representative (USTR) on imports from Thailand has generated additional pressure on the Thai seafood industry, particularly across the supply chains for shrimp (Penaeus vannamei) and tuna (Thunnus spp.).
Although the commercial framework was formally announced by Washington in 2025, its effects on operating margins, contract renegotiations, and international competitiveness remain a central concern. While the USTR left open the possibility of exempting specific key products (applying a 0% rate), official documents do not explicitly list processed seafood among these exemptions.
For its part, Thailand’s Department of International Trade Promotion (DITP) ratified the validity of the 19% tariff, noting that the agreement aims to preserve access to the country's primary export destination market in exchange for greater domestic market opening to US products.
The Shrimp Sector Faces the Highest Commercial Risk
Thai shrimp competes directly in the United States market with large-scale global suppliers such as India, Ecuador, Indonesia, and Vietnam. The imposition of the 19% tariff presents exporters with a dilemma: pass the cost on to North American buyers and importers — running the risk of losing market share — or absorb the tax by lowering prices at origin, which severely impacts plant profitability.
This juncture comes at a critical moment for the Thai shrimp farming sector, which is undergoing a recovery process following years of aquaculture disease impacts, rising input costs, and climate variations. Organizations like the Thai Shrimp Association have requested government support measures to recover national harvest volumes, while processing plants need to maintain high levels of installed capacity utilization to amortize fixed costs.
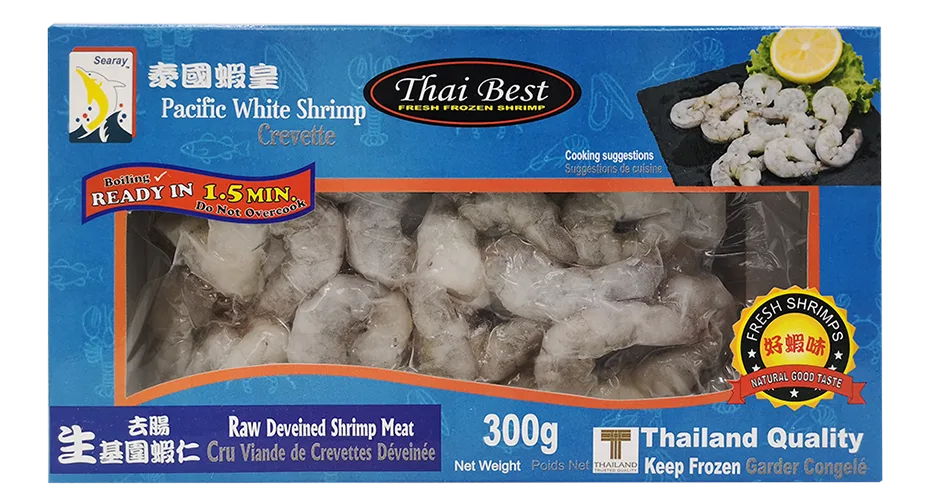
Photo: Stockfile / FIS
According to projections by the Department of Fisheries published by Nation Thailand, Thai seafood shipments to the United States represent approximately 21.79% of the total export value of the sector, registering an average annual volume of 236,255 metric tons and a value of 46,410 million baht. Sectoral analysis predicts that exports to this destination could experience a decline of between 5% and 10%, which would represent an estimated economic loss of between 2,410 million baht and 4,820 million baht.
Tuna: Impact on Raw Materials and the Canning Industry
In the tuna segment, the structure of the impact differs from that of shrimp. Thailand is positioned as the world's largest processing and export hub for canned tuna, relying heavily on imports of frozen raw material from international fleets. The application of the US tariff affects both the competitiveness of the final packaged product and the logistical planning of processing facilities.
Facing the new tariff structure, processors affiliated with the Thai Tuna Industry Association (TTIA) are evaluating four strategic alternatives:
-
Partially absorb the cost of the tariff by adjusting margins.
-
Renegotiate final sales prices with US retail chains.
-
Redirect export volumes toward alternative markets in Europe, Asia, or the Middle East.
-
Modify product presentations, formulations, and lower-value-added blends.
Records from the TTIA will serve as a key metric to determine whether the commercial contraction concentrates on canned tuna, pre-cooked loins, ready-to-eat preparations, or frozen tuna.
Tariff Comparison Against Direct Competitors
Despite the tax impact, Thailand does not find itself in an absolute disadvantage relative to its competitors in the US market, as Washington applies similar reciprocal tariffs to other key supply origins:
-
India: 25%
-
Vietnam: 20%
-
Thailand: 19%
-
Indonesia: 19%
-
Ecuador: 15%
While the narrow tariff differential mitigates the risk of immediate supplier substitution, the 19% rate increases overall upward pressure on final consumer prices. Furthermore, for shrimp specifically, the effective import rate in the United States may exceed 19% due to the additional application of specific anti-dumping or countervailing duties depending on each company and country of origin.
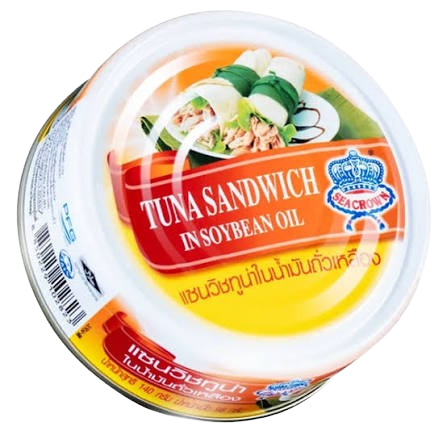 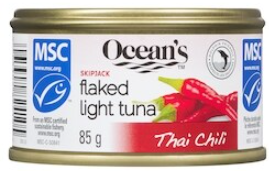
Photo: Stockfile / FIS
Repercussions for the United States Import Market
For importers and distributors in the United States, the new tariff structure implies higher replacement costs for shrimp and canned tuna. However, complete replacement of Thai supply is difficult in the short term, given Thailand's integrated industrial infrastructure, international quality certifications, and capacity to consistently supply large volumes.
Industry specialists anticipate that tariff pressure will primarily affect lower-margin product lines first, while premium categories, private labels, and convenience formats will retain greater cost-absorption capacity within the North American market.
🇯🇵 日本語 (Japanese Version) | AIによる自動翻訳
米国による19%の関税がタイ産ツナおよびエビの競争力を脅かす
ワシントンが課した措置は輸出マージンを圧迫し、水産部門の売上予測を押し下げるとともに、エクアドル、インド、ベトナムなどの競合国との競争構図を再編している。
タイ / 米国 — 米国通商代表部(USTR)がタイからの輸入品に対して19%の相互関税率を適用することを手続上確認したことで、タイの水産業界、特にエビ(Penaeus vannamei)およびツナ(キハダ・カツオ類)(Thunnus spp.)のサプライチェーン全体に新たな圧力が加わっている。
この貿易枠組み自体は2025年にワシントンから正式発表されたものであり、新しいニュースではないものの、営業利益率、契約改定、および国際競争力への影響は引き続き業界にとって重大な懸念事項である。USTRは特定の商品について関税免除(0%税率)の可能性を残しているが、公式文書には加工済みの水産物がその除外リストに明記されていない。
一方、タイ国際貿易推進局(DITP)も19%の税率が有効であることを確認しており、本合意は米国製品に対する自国市場の開放拡大と引き換えに、タイにとって最大の輸出市場へのアクセスを維持することを目的としたものであると説明している。
エビ部門が最大の商業的リスクを抱える
タイ産のエビは、米国市場においてインド、エクアドル、インドネシア、ベトナムなどの大規模なグローバル供給国と直接競合している。19%の追加関税の課税は輸出業者に厳しい選択を迫っている。費用を北米の輸入業者や買い手に転嫁して市場シェアを失うリスクを冒すか、現地出荷価格を引き下げて税金を自社吸収し、加工工場の収益性を大幅に悪化させるかである。
この局面的課題は、養殖病害、資材コストの増加、気象変動の影響を受けた数年間の打撃から回復を模索しているタイのエビ養殖業界にとって特に深刻である。タイエビ協会(Thai Shrimp Association)は国内収穫量を回復させるための政府支援策を要請しており、加工業者側も固定費を償却するために工場の稼働率を高水準に維持する必要に迫られている。
Nation Thailandが報じた水産局(Department of Fisheries)の試算によると、タイの対米水産物輸出は同部門の総輸出額の約21.79%を占めており、年平均236,255トン、金額にして464億1,000万バーツに達する。同分析では、対米輸出量が5%から10%減少する可能性が予測されており、金額換算で24億1,000万バーツから48億2,000万バーツの経済損失に相当する。
ツナ:原材料および缶詰産業への影響
ツナ分野における影響の構造はエビとは異なる。タイは世界最大のツナ缶加工・輸出拠点であり、海外の遠洋漁業船団からの原料魚の輸入に大きく依存している。米国の関税適用は、最終製品である缶詰の価格競争力だけでなく、工場の原料調達戦略にも影響を与える。
新たな関税構造に直面し、タイツナ業界協会(TTIA)に加盟する加工業者は以下の4つの戦略的代替案を検討している。
-
マージンを調整して関税コストの一部を自社吸収する。
-
米国の小売・流通チェーンと最終販売価格の再交渉を行う。
-
輸出先を欧州、アジア、中東などの代替市場へ転換する。
-
製品仕様、配合比率、または低付加価値商品の構成を変更する。
貿易収縮がツナ缶、蒸しロイン(プレクック)、調理済み簡便食、または冷凍ツナのいずれに集中するかを見極める上で、TTIAの統計データが重要な指標となる。
競合国との関税比較
税負担の増大はあるものの、米国が他の主要供給国に対しても同様の相互関税を適用しているため、タイが絶対的な関税上の不利に立たされているわけではない。
-
インド: 25%
-
ベトナム: 20%
-
タイ: 19%
-
インドネシア: 19%
-
エクアドル: 15%
関税率の差が比較的小さいことから、急激な供給国変更のリスクは一定程度抑えられるものの、19%の税率は米国内での最終消費者価格を押し上げる要因となる。さらにエビに関しては、企業や原産国ごとに個別の相殺関税や反ダンピング関税が加算される場合があるため、実質的な適用税率は19%を上回る可能性がある。
米国輸入市場への影響
米国の輸入業者および流通業者にとって、新しい関税枠組みはエビおよびツナ缶の調達コストの上昇を意味する。しかし、タイの統合された産業インフラ、国際的な品質認証、そして安定した大量供給能力を考慮すると、短期間での完全な代替調達先の確保は困難である。
業界の専門家は、関税圧力の影響はまず利益率の低い低価格帯商品に現れ、プレミアムライン、プライベートブランド、簡便性製品については北米市場でのコスト吸収力が比較的高く維持されると予測している。
🇨🇳 中文 (Simplified Chinese Version) | 由人工智能自动翻译
美国19%关税威胁泰国金枪鱼和对虾的市场竞争力
华盛顿实施的这一关税措施给出口利润率带来压力,下调了水产行业的销售预期,并重塑了与厄瓜多尔、印度和越南等国的竞争格局。
泰国 / 美国 — 美国贸易代表办公室(USTR)确认对来自泰国的进口商品实施19%的互惠关税税率,这给泰国水产行业带来了额外的压力,尤其是对对虾(Penaeus vannamei)和金枪鱼(Thunnus spp.)的价值链造成了明显冲击。
尽管该贸易框架由华盛顿于2025年正式宣布,但其对运营利润率、合同重新谈判以及国际竞争力的后续影响依然是该行业关注的核心焦点。虽然USTR保留了对部分特定关键产品给予豁免(适用0%税率)的可能性,但官方文件并未明确将加工水产品列入该豁免清单。
与此同时,泰国国际贸易促进厅(DITP)证实了19%关税税率的有效性,并指出该协议旨在以扩大泰国国内市场对美国产品的开放为条件,保留对泰国最大出口目的国市场的进入权限。
对虾部门面临最大的商业风险
泰国对虾在美国市场上面临来自印度、厄瓜多尔、印度尼西亚和越南等大规模全球供应国的直接竞争。加征19%的关税给出口商带来两难选择:要么将成本转嫁给北美进口商和买家——但这面临失去市场份额的风险;要么通过降低出厂价格来消化税负,而这将严重损害加工厂的盈利能力。
这一局面对泰国对虾养殖业而言尤为严峻。近年来,该行业一直在努力从水产疾病、生产成本上升以及气候变化带来的影响中恢复。泰国对虾协会(Thai Shrimp Association)已要求政府采取支持措施以恢复全国捕捞与养殖产量,而加工厂则需要维持较高的产能利用率以摊薄固定成本。
根据泰国国家报(Nation Thailand)引用的水产厅(Department of Fisheries)分析数据,泰国对美国的水产品出口约占该部门出口总值的21.79%,年均出口量为236,255公吨,总价值达464.10亿铢。行业分析预计,对该目的地的出口量可能下降5%至10%,相当于造成24.10亿铢至48.20亿铢的经济损失。
金枪鱼:对原料及罐头加工业的影响
在金枪鱼领域,关税带来的影响结构与对虾有所不同。泰国是全球最大的金枪鱼罐头加工和出口中心,高度依赖来自国际远洋渔船的大量冻鱼原料进口。美国关税的实施既影响包装成品在终端市场的竞争力,也影响加工厂的原料采购与物流策略。
面对新的关税结构,隶属于泰国金枪鱼行业协会(TTIA)的加工商正在评估四项战略替代方案:
-
通过调整利润率自行消化部分关税成本。
-
与美国零售分销商重新谈判最终销售价格。
-
将出口份额转向欧洲、亚洲或中东等替代市场。
-
调整产品呈现形式、配方及低附加值产品的组合。
TTIA的统计数据将成为衡量出口收缩是集中在金枪鱼罐头、预熟鱼柳、即食方便食品还是冻金枪鱼上的关键指标。
与直接竞争对手的关税对比
尽管承受税负压力,但泰国在美市场上并不必然处于绝对关税劣势,因为华盛顿对其他主要供应国同样征收了类似的互惠关税:
-
印度:25%
-
越南:20%
-
泰国:19%
-
印度尼西亚:19%
-
厄瓜多尔:15%
微小的关税差距降低了采购商立即更换供应国的风险,但19%的税率整体上推高了终端消费者的价格压力。此外,就对虾而言,由于针对不同企业及原产国可能加征额外的反倾销税或反补贴税,实际有效进口税率可能高于19%。
对美国进口市场的影响
对于美国的进口商和分销商而言,新关税架构意味着对虾和金枪鱼罐头的重置成本有所增加。然而,考虑到泰国拥有完善的集成工业基础设施、国际质量认证以及持续供应大宗标准规格产品的能力,短期内完全替代泰国供应极为困难。
行业专家预测,关税压力将首先传导至低利润率产品线,而高端系列、自有品牌和方便食品在北美市场上则具备较强的成本消化能力。
[email protected]
www.seafood.media
|

 Print